Insurance built for the way associationstownhomescondosassociations actually work.
We insure townhome, condo and homeowners associations. Only that. Which is why boards and property managers across Minnesota trust us with the roofs over hundreds of communities.
New · Interactive
Walk through a community we insure.
Y2K Village is a 48-unit townhome association. Walk the street, step inside a unit, then visit the pool, the playground and the clubhouse, and see which policy answers at each one.
Replacement cost, not actual cash value.
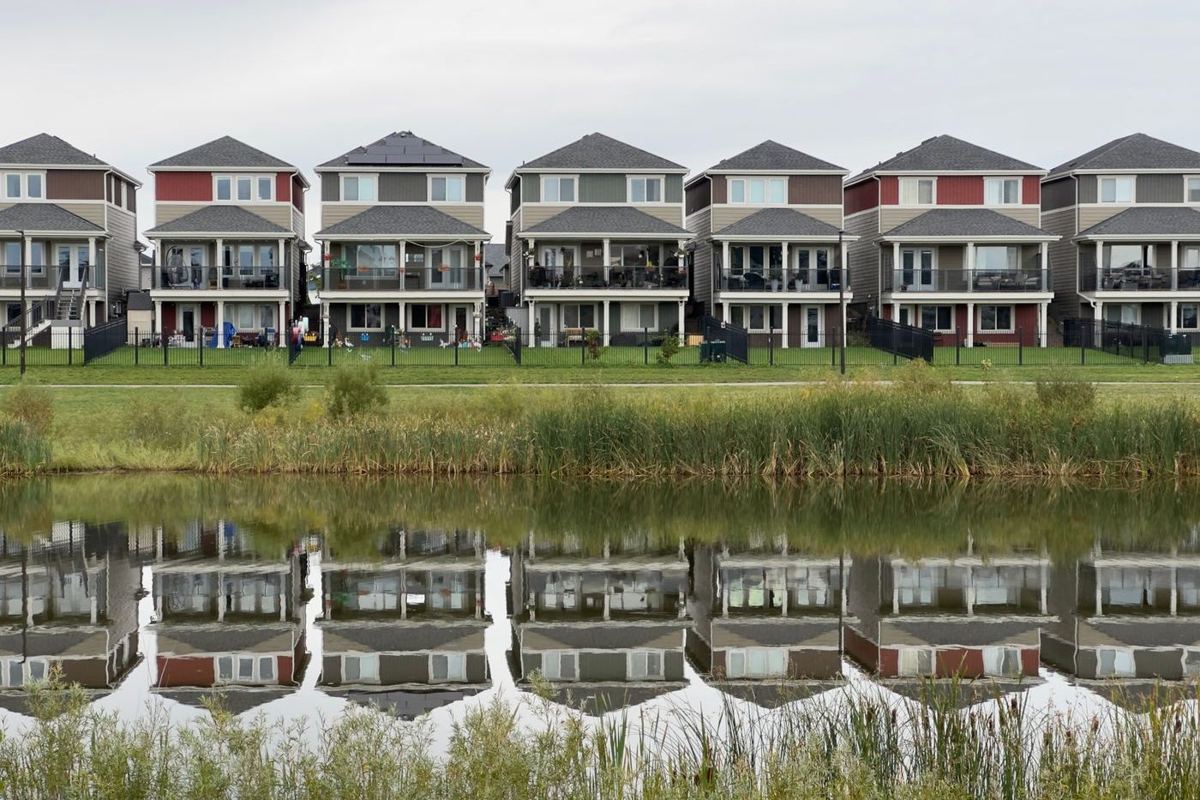
There are two ways a policy can pay for these roofs. Replacement cost puts a new roof on. Actual cash value pays what the old roof was worth after depreciation, and on 15-year-old shingles that can be half the bill, with the association writing a check for the rest. Carriers are quietly adding ACV roof endorsements and age schedules at renewal. We flag them, fight them, and price the difference so the board decides with its eyes open.
Property coverageAll-in, original specs, or bare walls?
One line in your declarations decides who rebuilds this kitchen after a fire. All-in: the master policy covers the unit as built, including cabinets, counters, flooring and fixtures; owners insure contents and upgrades. Original specifications: the master policy covers what the builder installed; anything an owner upgraded is on their HO-6. Bare walls: the master policy stops at the drywall; everything in this room is the owner’s. A board resolution can change it. We read the documents and match the policy before you bind.
Coverage definition explainedSomeone is hurt at the pool.
A visitor slips on the deck. A gate latch fails. The association’s liability policy answers, and the duty to defend starts the day you report it.
Liability coverageA swing chain breaks. A child falls.
Medical payments pays the small ones fast, without a lawsuit. Liability stands behind the big one. Both live on the same policy, and we make sure the limits fit the equipment you actually have.
Playground inspections and coverageWhere the board votes.
Volunteers make real decisions with real money. When owners sue over an assessment vote, D&O keeps the lawsuit from reaching the board members’ own homes.
D&O coverageThe plow truck backs into three cars.
Snow contractors, landscapers, a board member driving to the bank for the association. Umbrella and hired non-owned auto cover the claim nobody budgeted for.
Umbrella coverageOne program. Every common area.
Property, liability, D&O, crime, umbrella and workers’ comp, placed together so nothing falls between policies. That is the whole job, and it is the only job we do.
Start your quoteMost agencies treat HOA insurance as a side offering. We do nothing else.
Associations come with their own risks, their own documents and their own rules under the Minnesota Common Interest Ownership Act. A generalist learns them on your account. We already know them.
That is what lets us find coverage others miss, and pricing others cannot match.
Six coverages. One team.
Swipe through them. If any card is missing from your current policy, that is where we start.
Property
The buildings, roofs and common areas, insured at what it actually costs to rebuild them.
Read how it works →
General Liability
Someone slips on a walkway or is hurt at the pool. This is the coverage that answers.
Read how it works →
Directors & Officers
Protects the volunteers on your board for the decisions they make on the association’s behalf.
Read how it works →
Crime & Fidelity
Covers theft or misuse of association funds, whoever has their hands on the checkbook.
Read how it works →
Umbrella
Extra liability limits above the primary policies, for the claim nobody planned for.
Read how it works →
Workers’ Compensation
Required even with no employees when volunteers and contractors do work for the association.
Read how it works →Is your association’s policy missing something?
Six quick questions about your current coverage. Most boards find at least one item they were not sure about. Swipe the cards or tap the buttons.
No quiz needed. Send us your current policy and we review it with you, no obligation.
How we work, in under a minute.
Two short films. One on how a renewal moves from request to board-ready proposal. One on keeping your community safe between renewals.
Ask us anything about HOA insurance.
Ninety-two real questions from boards, property managers and unit owners, answered in plain English. Start typing, or pick a topic.
Ask our 24/7 AI assistant any time. For a real person, email associations@myinsurancewarehouse.com during business hours.
Insurance Warehouse has been there for us, for years. We couldn’t imagine using any other insurance agency. Their service is always incredibly fast, and they proactively look out for us when our policies renew.Association client · Google review
Ready for a second opinion on your policy?
Send us what you have. We review it, show you the gaps in plain English, and there is no obligation to work with us afterward.
Take a break
Play a game about HOA claims
🌪Steer the StormMiss the buildings. Save the policy limit. 🏈Claim BlitzRun the claim file to the end zone.Two minutes each. Works on your phone.